Real Estate & Property
More Listings, Loan Applications and Closed Deals
We help brokerages, lenders, title agencies, property managers and inspectors across the five boroughs and Long Island win the searches that end in a signed agreement, inside the advertising rules that come with your license.
Why it works
Reaching clients where they search
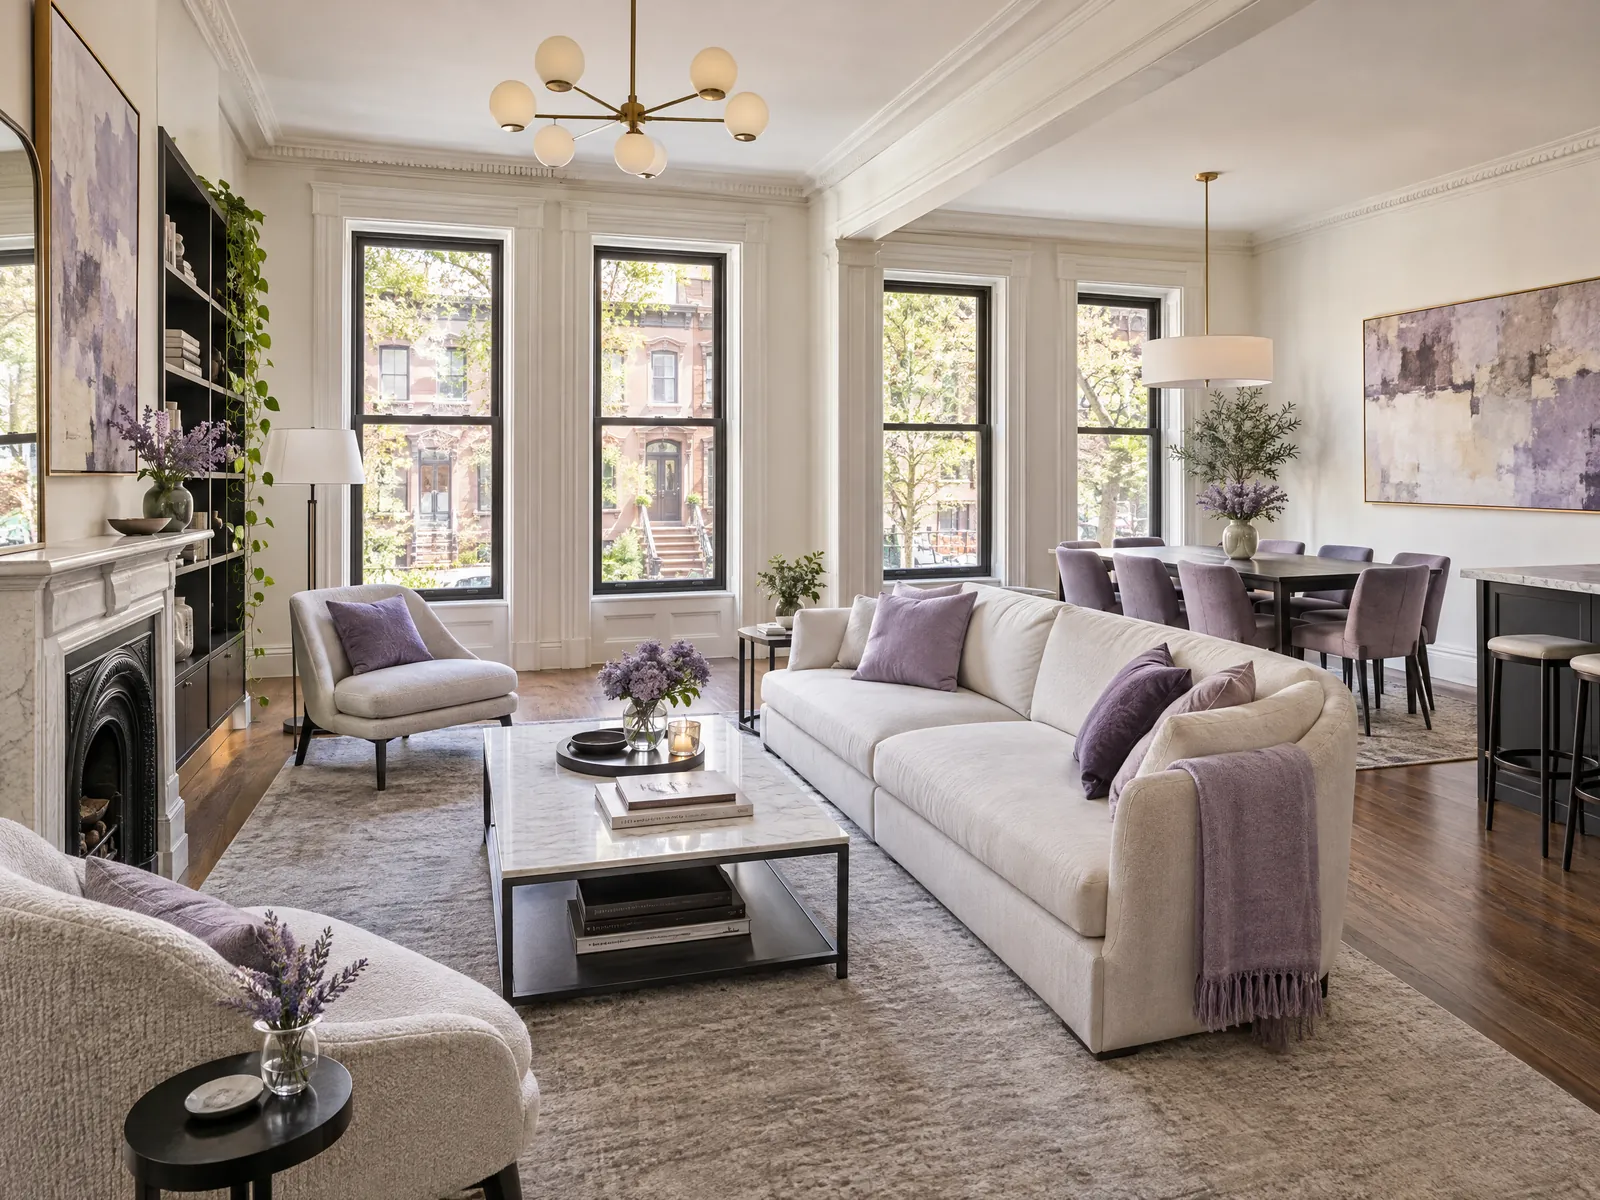
One home sale puts half a dozen businesses to work, and most of them get chosen online. A seller in Bayside reads agent reviews before picking who lists the house. The buyer compares loan officers on a phone during a lunch break in Hicksville. Once the offer is accepted, someone has a few days to book an inspector for a 1950s cape in Great Kills. Meanwhile a landlord with three buildings on the Grand Concourse is looking for a manager who returns calls. Every one of those searches is a customer for somebody.
We build the pieces that win them. Google Business Profiles for each office, and for the agents and loan officers Google allows. Websites with neighborhood, loan and inspection content written for New York. Reviews that keep coming in honestly. Ads set up in the housing and credit categories on the first build, with the brokerage name, NMLS ID or license number already in place. AI-assisted tools speed up our research, drafting and reporting, and a person on our team reviews everything before it reaches you. Each month you see calls, form leads and booked appointments by source.
We start with Google Maps
Sellers, borrowers and buyers with an accepted offer all check the map before they call. We tune your categories, service areas, photos and posts, then track your rank on a local search grid, so you can see where you show up in Forest Hills versus Rego Park, or Garden City versus Mineola, and which blocks still belong to a competitor.
Housing and credit ads built right the first time
Listing, rental and mortgage ads run in restricted categories on Google and Meta, with no targeting by age, gender or ZIP code. We plan around those limits from day one and lean on search intent, location and creative, so you are not rebuilding campaigns after a rejection.
License details baked into every template
Brokers, mortgage companies and home inspectors in New York each have their own list of what an ad must show. We put the brokerage name, NMLS IDs, licensing legends and license numbers into ad templates, site footers and social bios, so nobody has to remember them at 10pm on a Sunday.
Experienced people, AI-assisted, human-reviewed
Our team brings years of hands-on local marketing work. AI helps us research keywords, draft pages and pull reports faster. A person edits every page and checks every number, and your broker of record or compliance officer approves anything regulated before it runs.
Specialties
Explore by specialty
Each specialty has a dedicated page covering the searches, challenges and strategies specific to that field.
 Real Estate Brokerages & AgentsWe help brokerages and agents across the five boroughs and Long Island win seller leads and buyer inquiries with local search, listing content and ads built for the housing rules.
 Mortgage Brokers & LendersWe help mortgage brokers, bankers and loan officers across the five boroughs and Long Island reach buyers and homeowners when they start shopping, with ads and pages that carry every required disclosure.
 Property ManagementWe help property managers across the boroughs and Long Island sign more buildings and lease more units, with marketing that talks to owners and tenants separately.
 Commercial Real EstateWe help commercial brokerages, landlords and investment sales teams reach the tenants, buyers and owners who decide where New York businesses set up shop, from Midtown towers to Hauppauge warehouses.
 Home InspectorsWe help licensed home inspectors across the five boroughs and Long Island get booked by buyers on a deadline, with marketing that never leans on the referral arrangements New York law prohibits.
 Title CompaniesWe help New York title agencies get chosen by the attorneys, lenders and agents who order title, with marketing built on expertise instead of inducements.
 Don't see your specialty?We work with many more. Tell us about yours in a free consultation.
Marketing within the rules
Real Estate, Lending and Inspection Advertising Rules
Housing, lending and inspection ads are regulated at the federal, state and city level, and the penalties are real. Here is how we keep your campaigns inside the rules. This describes how we run our work. It is not legal advice, and your attorney, broker of record or compliance officer has the final word on your obligations.
This is how we approach marketing, not legal advice. Your own counsel has the final word on compliance.
- Fair Housing Act: ads for the sale or rental of housing may not indicate a preference, limitation or discrimination based on race, color, religion, sex, disability, familial status or national origin (42 U.S.C. 3604(c)). We write copy about the property, the loan or the service, never about the ideal buyer, tenant or borrower.
- New York's Human Rights Law adds protected classes, including lawful source of income such as Section 8 vouchers and other housing assistance. Rental ads never include 'no vouchers' or 'no programs' language.
- Google bars housing and credit advertisers in the U.S. from targeting or excluding people by gender, age, parental status, marital status or ZIP code. Meta requires a special ad category for these campaigns: Housing for listings and rentals, and Financial Products and Services, which replaced the old Credit category in January 2025, for loans and other credit. Both remove age and gender targeting, ZIP code targeting and lookalike audiences, and require a minimum 15-mile radius around any location.
- New York's advertising rule for real estate licensees (19 NYCRR 175.25) requires ads to identify the broker or brokerage with its address or phone number. Agents appear under their licensed name and correct license type, team names include the word 'team', and agent websites carry the required details on every page. Another broker's exclusive listing appears only with permission and a 'Listing Courtesy of' credit.
- New York brokers must post dated, notarized Standardized Operating Procedures for prospective homebuyers on their websites and apps (Real Property Law 442-H). We make sure that page is published and easy to find.
- RESPA Section 8 bars giving or accepting anything of value for referrals of settlement business on federally related mortgage loans, which covers lenders, mortgage brokers and title agencies. For title companies, New York Insurance Law 6409(d) and DFS Regulation 208 also bar meals, entertainment and gifts as inducements. Our referral marketing runs on content and advertising, never on paid referrals.
- NYC's FARE Act, in effect since June 11, 2025, bars a landlord's agent from charging tenants a broker fee and requires rental listings to disclose every fee a tenant must pay. Our ads for city rentals show those fees.
- DFS rules for mortgage advertising (3 NYCRR 38.2) require a licensing legend such as 'Registered Mortgage Broker' or 'Licensed Mortgage Banker' with the state regulator named, plus the company name and a New York office address. Brokers must make clear they arrange loans through third-party lenders. Claims of 'immediate approval' or 'immediate closing' are treated as deceptive, and an advertised rate must note that it can change before commitment or closing.
- The SAFE Act model state law, which most states have adopted, calls for a loan originator's NMLS unique identifier on advertisements, solicitations and websites. We show the company's NMLS ID, and the ID of any loan officer named, on every ad and page, and we link to NMLS Consumer Access. Your compliance officer confirms the New York specifics.
- Truth in Lending (Regulation Z, 12 CFR 1026.24): a rate in an ad must be stated as an APR, and trigger terms such as the down payment, the number of payments or the payment amount require the down payment, the repayment terms and the APR to run with them. We would rather send people to a rate quote than squeeze those disclosures into a 90-character ad.
- Banks supervised by the FDIC must carry the Equal Housing Lender logo and legend, or HUD's Equal Housing Opportunity logo, on written ads for home loans (12 CFR 338.3), and many nonbank lenders and brokers use the Equal Housing Opportunity logo as well. We use the version your compliance team specifies, at a size people can actually read.
- New York requires every licensed home inspector to show the license number and licensed status in all advertising and on every report (Real Property Law 444-g). The same section bars inspectors from paying commissions, referral fees or kickbacks to sellers or agents, and from offering paid repairs on a home they inspected before the closing.
- The FTC's Consumer Reviews and Testimonials Rule (16 CFR Part 465) bans fake reviews, buying reviews and incentives tied to positive or negative sentiment. Google bans any incentive for reviews and bans asking only happy customers. We ask every client the same way, offer no rewards and never screen who gets the review link.
Ready to attract more clients?
We will review how you appear on Google and Maps today, where competitors are ahead, and what we would prioritize first. No obligation.